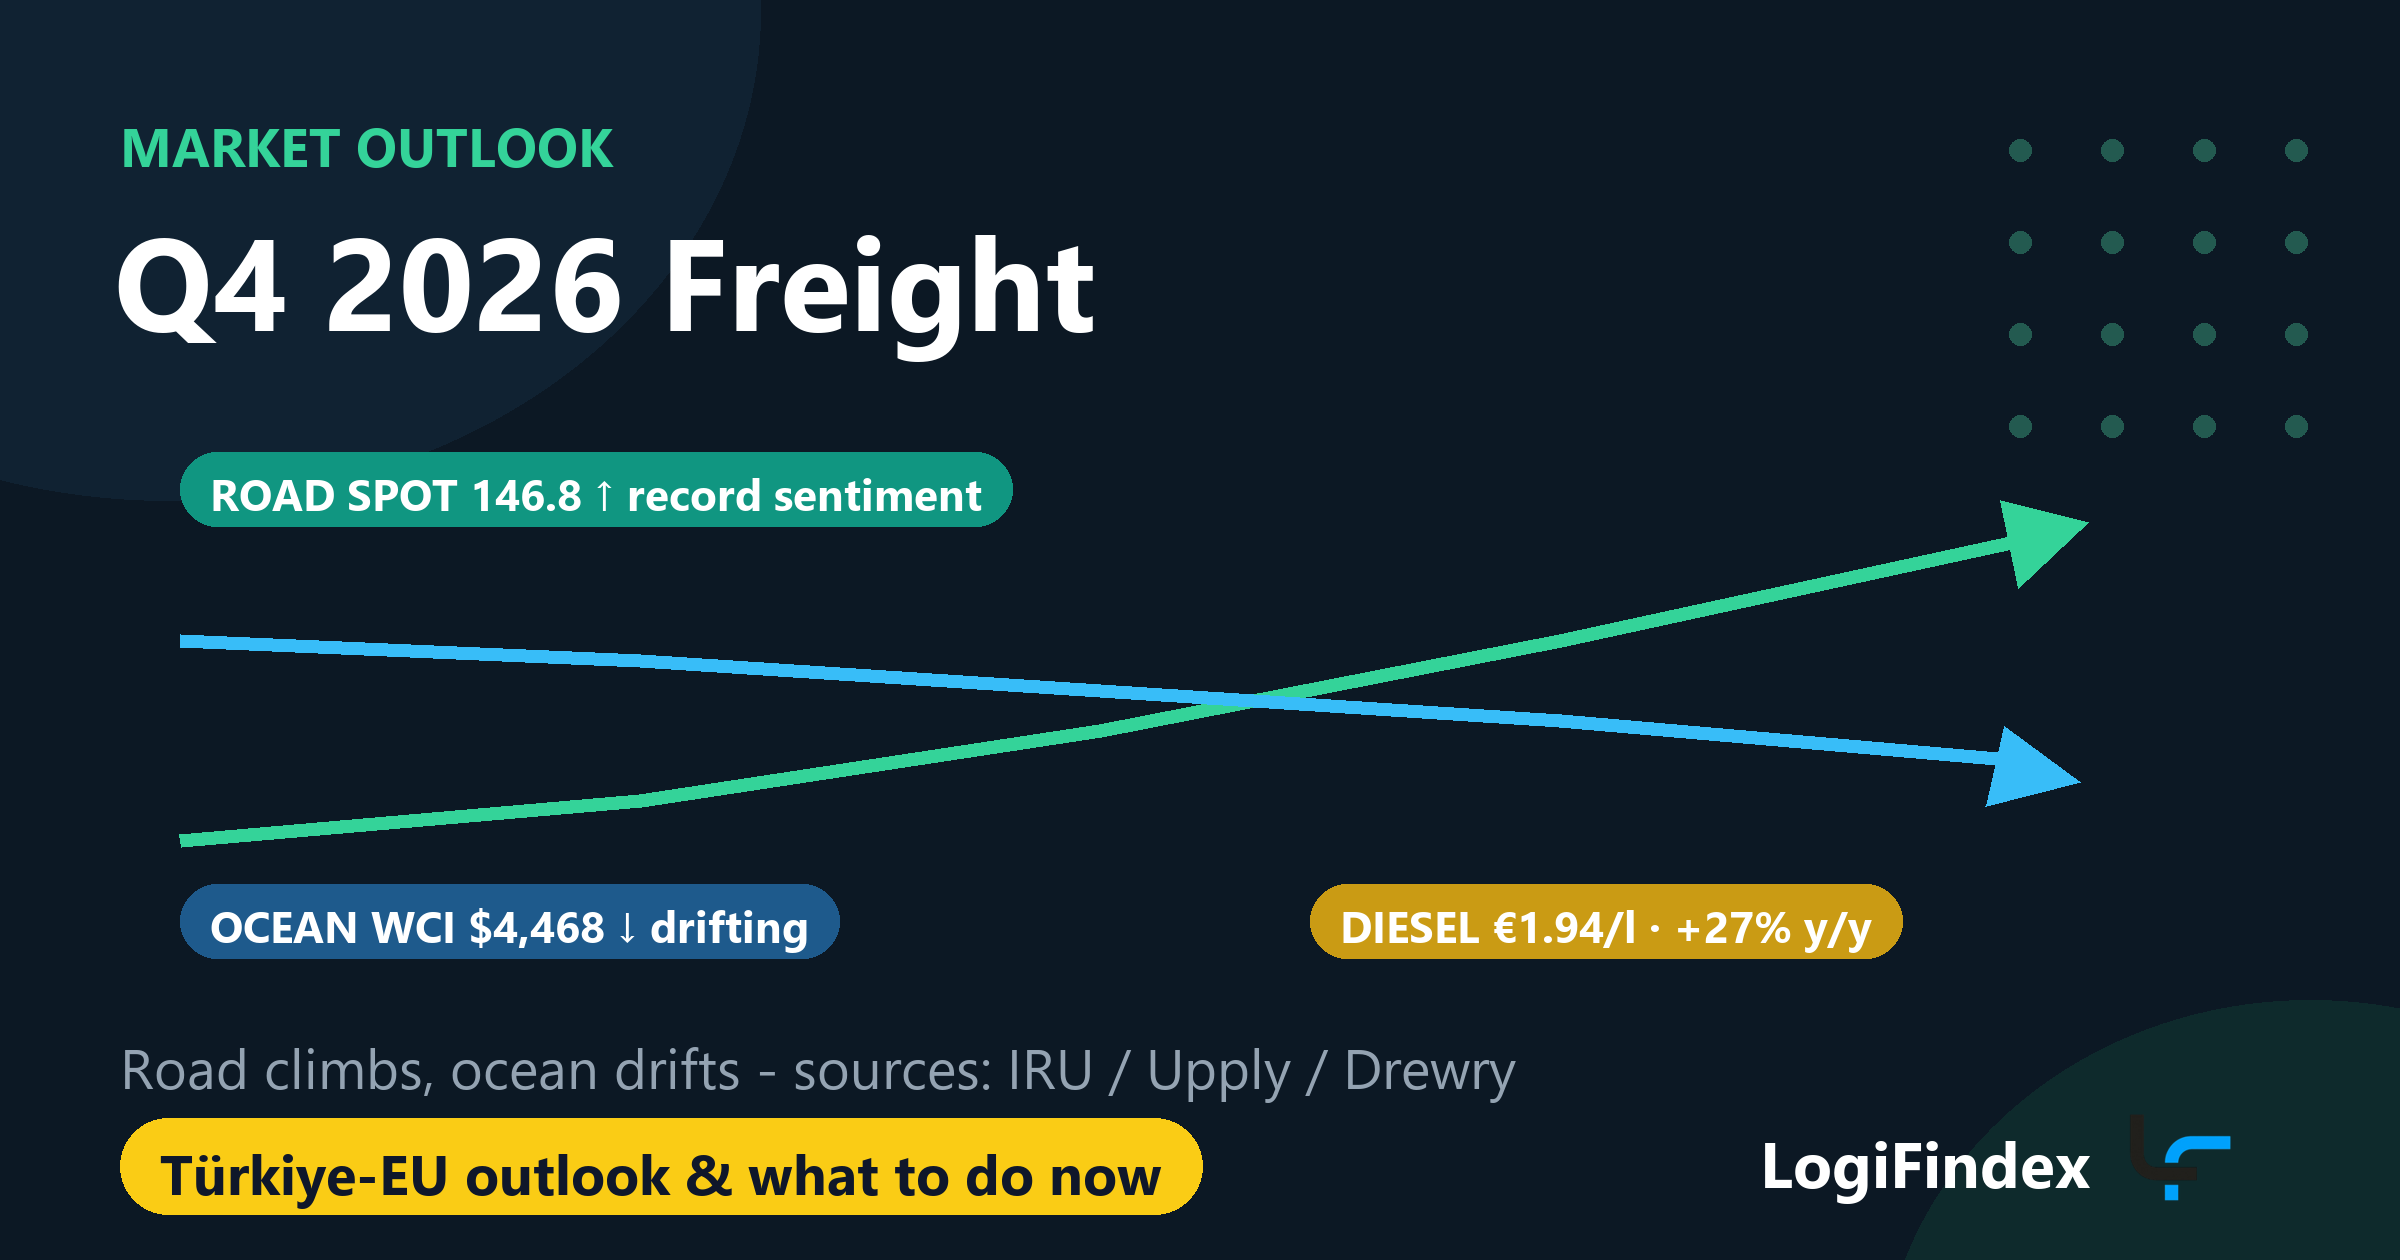
The data points one way for European road freight this quarter: up. The Ti / Upply / IRU benchmark put Q2 2026 spot rates at 146.8 points (+14.6 quarter-on-quarter) with the sentiment index at a record 28.3, EU diesel averaged €1.94/litre after February's Iran shock (+27% year-on-year), and Q4 adds its own seasonal squeeze: year-end peak volumes, transit-permit scarcity and winter. Ocean container rates, by contrast, are drifting down. For Türkiye-EU shippers the practical read is: book Q4 road capacity early, expect mid-single-digit upward pressure, and quote sea or Ro-Ro alternatives where the calendar allows.
This is an informational market outlook, not a price commitment. Every figure below carries its source; freight is repriced weekly.
What the Mid-Year Data Actually Says
The broadest European road benchmark - published jointly by Ti, Upply and the IRU - showed both markets accelerating in Q2 2026: contract rates at 148.0 points (+7.9 q/q, +15.2 y/y) and spot rates at 146.8 points (+14.6 q/q, +13.9 y/y). After three quarters of divergence, spot and contract are rising together - and the report is blunt about the driver: cost, not demand.
The cost in question is fuel. Following the outbreak of the Iran conflict in late February 2026, EU diesel averaged €1.94 per litre in Q2 - up 12% on the quarter and 27% on the year (Ti Insight). Diesel is roughly a third of a truck's operating cost; moves of this size do not stay out of freight for long.
Most telling is expectation: the road freight sentiment index jumped 11.4 points to 28.3 - its highest reading on record (Upply), meaning the market itself is positioned for further increases over the following three months. That following period is, give or take, the quarter we are now in.
Meanwhile, Ocean Is Going the Other Way
Deep-sea container freight tells the opposite story: Drewry's World Container Index stood at $4,468 per 40ft in late September, down 1% on the week, with Asia-Europe softening and carriers announcing blank sailings into China's Golden Week (Drewry WCI). The divergence matters for Türkiye-EU shippers directly: where your cargo and calendar permit a sea or sea-assisted routing, the pricing wind is at your back - the trade-offs are mapped in our Ro-Ro guide and the Netherlands lane guide.
The Türkiye Angle: Three Local Multipliers
- Fuel and currency at home. Diesel at Turkish pumps hovered around 93-94 TL/litre in late September after a volatile month of cuts and hikes, with the euro near 56 TL. Carriers buying fuel in lira and billing in euro watch both lines; sustained lira weakness cushions euro-denominated rates, while fuel spikes push the other way.
- Year-end permit scarcity. Bilateral transit permits thin out every Q4, concentrating trucks on fewer routings and amplifying border queues - the mechanics and the alternatives are in our Kapıkule guide.
- Peak-season demand. Pre-Christmas retail stocking across Europe lands exactly on this quarter. Capacity tightens first on the lanes Turkish exporters use most.
Three Scenarios for Q4
- Base case - grinding upward. Fuel stabilises near current levels; seasonal demand and permit scarcity do the rest. Türkiye-EU road rates end the year moderately higher - think mid-single-digit percentage pressure, more on spot than contract.
- Upside risk - another energy shock. The February pattern repeats via geopolitics; diesel jumps again and surcharge clauses activate within weeks. Record sentiment says the market would reprice fast.
- Downside case - demand disappoints. European consumption stays weak enough to blunt peak season; road rates plateau rather than fall (costs have ratcheted), while ocean keeps drifting down.
What a Shipper Should Actually Do Now
- Book November-December loadings early - capacity scarcity, not list price, is what hurts in a peak quarter.
- Rebalance contract vs spot: with spot climbing faster than contract, locking regular volumes while quoting the remainder has rarely looked better - the arithmetic is in our freight cost guide.
- Mind the surcharge lines, not just the headline rate: fuel (BAF-style) clauses are where a Q4 shock would land first - see what the surcharges mean.
- Quote alternatives side by side: road, Ro-Ro and sea answer differently this quarter; make them compete on the same screen.
Test any quote against the market in minutes. Post your load once on LogiFindex and collect competing carrier offers - or run a free price check on the quote already in your inbox. Commission: 0%.